
Are Car Modifications Covered by Insurance in Florida?
Added a lift kit, custom wheels, a sound system, or performance parts? A standard Florida policy usually won't fully cover them, and not disclosing them can sink a claim. We explain Custom Parts and Equipment coverage, what it costs, what it covers, and where mods raise your rate.

Eddie Ezekiel
Published Jul 6, 2026 · 5 min read
Updated Sep 7, 2026
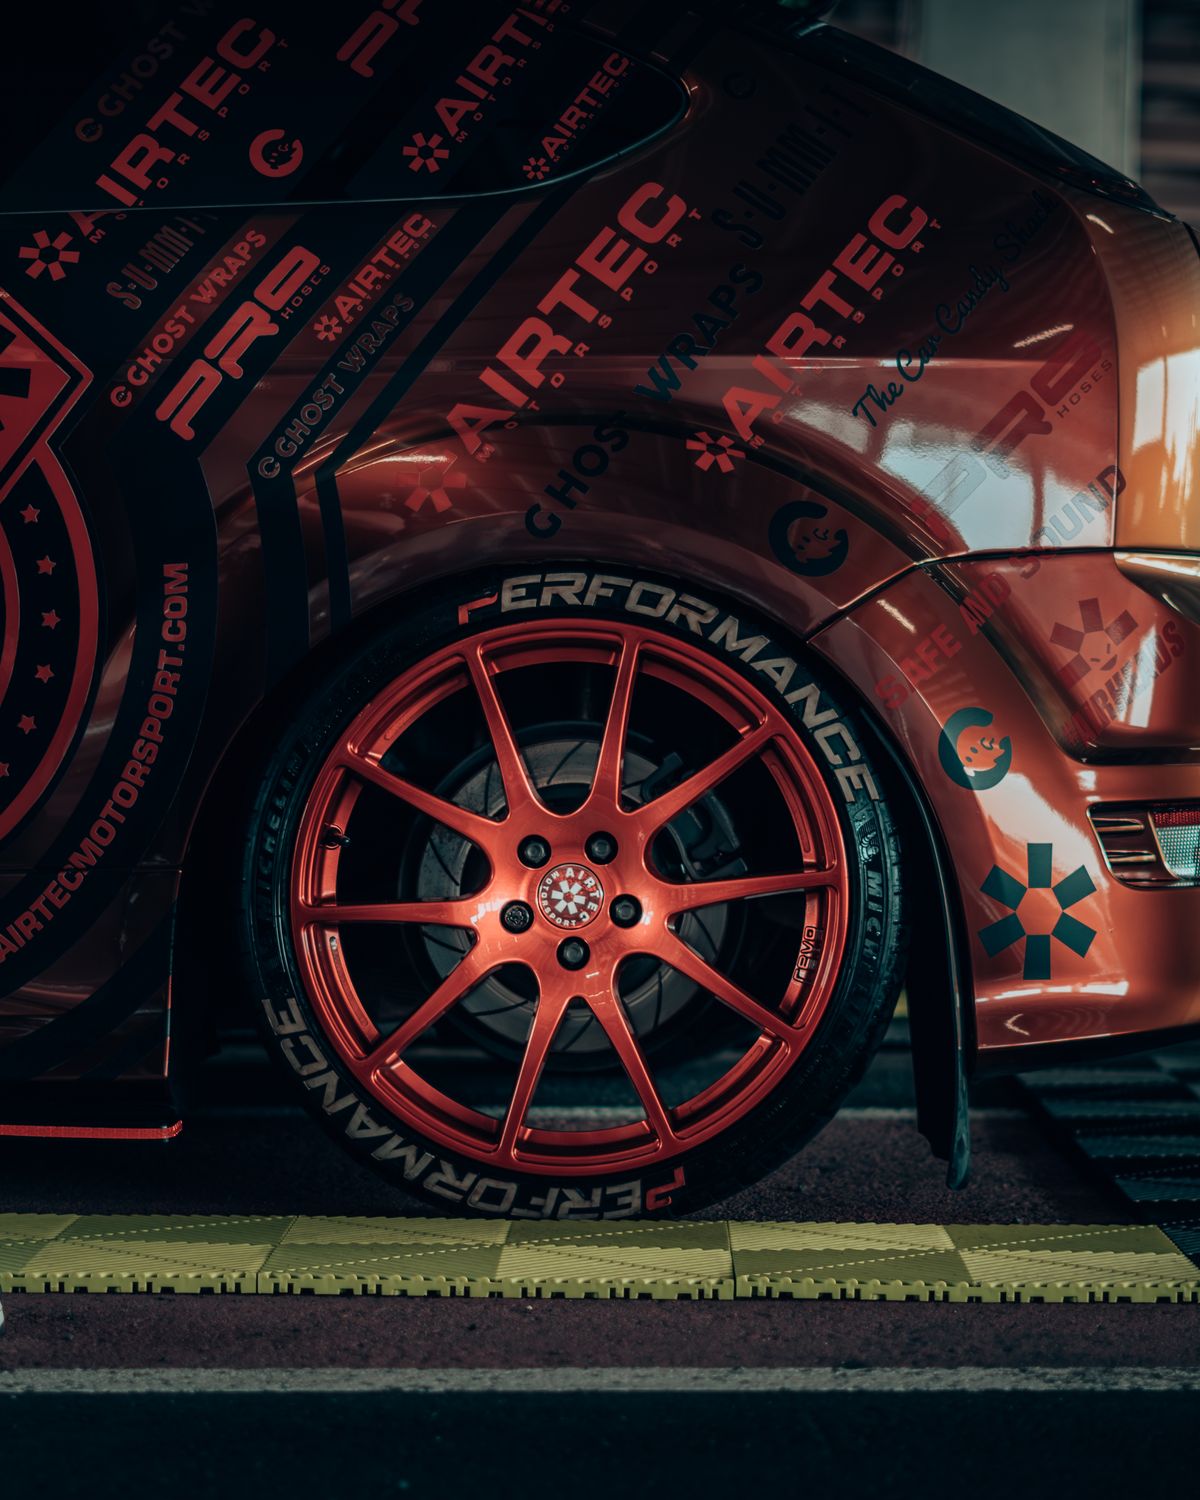
Image credit: Photo by Maja Kos on Pexels
You dropped real money on a lift kit, custom wheels, a serious sound system, or performance parts. Now the question that should have come first: does your insurance actually cover any of it? In Florida, the honest answer is usually 'not much, unless you set it up on purpose.' A standard policy is built around the car's factory value, hiding modifications in a coverage gap that only appears at claim time. Below, we explain exactly how modification coverage works, what it costs to fix the gap, what is and is not covered, and where mods can raise your rate or void coverage altogether.
Why a standard policy leaves a gap
Your comprehensive and collision coverage is built around the car's factory value. Factory-installed options are baked into that value and covered normally. Aftermarket additions are different. Many policies include only a small amount of coverage for custom parts, often about $1,000, and some exclude aftermarket equipment entirely unless you add an endorsement. So if a $6,000 audio-and-wheel build is stolen or destroyed in a covered loss, a bare policy might pay a fraction of it, or nothing beyond the factory car.
The coverage that actually protects mods: CPE
The fix is Custom Parts and Equipment (CPE) coverage, an endorsement that raises the limit for your aftermarket additions to an amount you choose. Per carinsurance.com, CPE endorsements typically let you insure between about $2,000 and $10,000 of custom parts, with $5,000 a common choice, and you pick the limit based on what you actually spent. It attaches to your comprehensive and collision coverage, so it only pays for mods when those coverages would pay for the car, and you need to carry them to add it.
What CPE covers, and what it doesn't
CPE is meant for permanent additions and alterations that change the car from its factory form. A rough guide:
| Usually covered by CPE | Usually not covered |
|---|---|
| Custom paint, wraps, and body kits | Normal wear and tear or mechanical breakdown |
| Aftermarket wheels and tires | Items you failed to disclose |
| Upgraded audio, video, and electronics | Tools or personal items in the car |
| Lift kits and custom suspension | Damage from racing or off-road misuse |
| Custom interiors, seats, and trim | Illegal modifications |
When mods raise your rate (or aren't covered at all)
Not every modification is just a coverage add-on. Some change how the insurer sees the risk:
- Performance upgrades (turbochargers, engine tuning, exhaust and intake work) can raise your premium, because a faster car is a higher-risk car, and some insurers will not cover heavily modified performance vehicles at all.
- Illegal modifications, such as certain window tints below Florida's legal limit or non-compliant exhausts, are not covered and can create other legal problems.
- Structural changes like extreme lifts may affect coverage or require a specialty insurer.
- Salvage or kit builds often need specialty or agreed-value policies rather than a standard one with a CPE endorsement.
How to insure your mods the right way
- Total up what you spent on modifications, with receipts, so you can set a CPE limit that actually reflects the value.
- Disclose everything to your insurer in writing, including performance work.
- Add CPE coverage at a limit that matches your build, and keep receipts and photos in case of a claim.
- Confirm the details: the per-loss limit, whether it applies to theft as well as collision, and any exclusions.
- Get a specialty quote too if your build is significant, and compare it against a standard policy plus CPE.
Frequently asked questions
Does standard car insurance cover modifications in Florida?
What is Custom Parts and Equipment coverage?
How much does CPE coverage cost?
Do I have to tell my insurer about modifications?
Will modifications raise my premium?
In Florida, your modifications are only as protected as you make them. A standard policy hides a gap that shows up at the worst possible moment, so total up what you spent, disclose every change, and add Custom Parts and Equipment coverage at a limit that matches your build, for around a hundred dollars a year. For a serious build, price a specialty or agreed-value policy too. The goal is simple: make sure the money you put into the car is money the insurer will actually pay back.
Last updated: Sep 7, 2026
Sources & references
We cite Florida statutes, the FLHSMV, and industry bodies like the Insurance Information Institute. How we research and maintain these guides. Spotted an error? Tell us.
About the author
Eddie Ezekiel
Eddie Ezekiel is a product and data specialist who builds digital tools for the insurance industry, including the website of Golden Eagle, an established insurance and financial-services firm. He founded FloRider to translate Florida's confusing car-insurance rules into plain English, with every claim traced back to primary sources like the FLHSMV.
Related reads

The 5-Year True Cost of Owning a Car in Florida
A car costs far more than its sticker price. Over five years in Florida, insurance is nearly the single biggest cost of ownership, rivaling depreciation. We break down where the money actually goes, and the one big cost you can actually cut.

The Cheapest and Most Expensive Cars to Insure in Florida
The car you choose can quadruple your insurance bill. We show the cheapest and most expensive vehicles to insure, with cited 2025 numbers, why the gap is so wide, and how much extra Florida drivers pay on top.

The Real Cost of Driving Uninsured in Florida
Skipping car insurance in Florida to save money is a trap. Getting caught suspends your license and triggers an expensive FR-44; crashing uninsured adds personal liability and a lawsuit. We add up what it really costs, both ways.