
The First 14 Days After a Florida Car Accident: A Step-by-Step Playbook
After a Florida crash, a clock most drivers don't know about starts ticking: you have 14 days to get medical treatment or you lose your PIP benefits entirely. This is exactly what to do, in order, from the scene through day 14.

Eddie Ezekiel
Published Aug 17, 2026 · 4 min read
Updated Sep 17, 2026
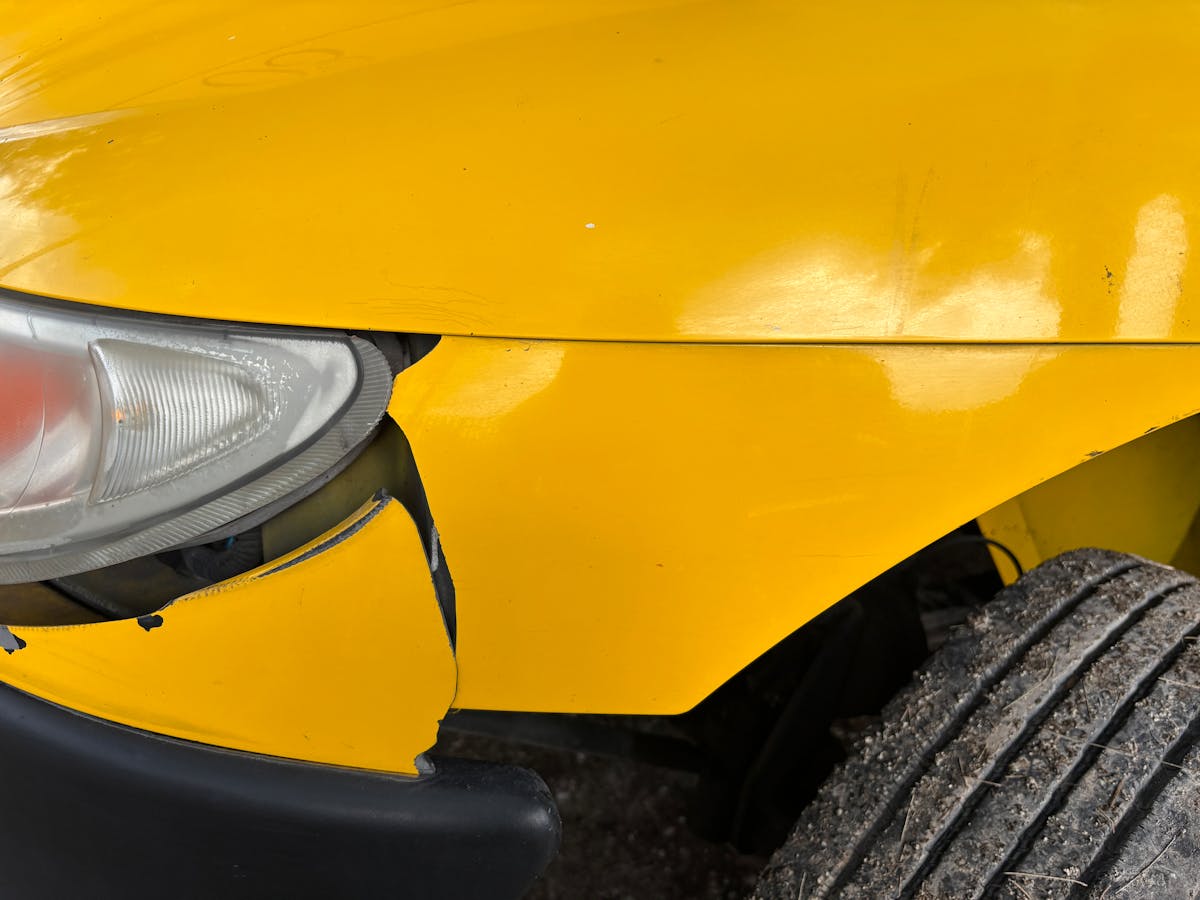
Image credit: Photo by Jorge Romero on Pexels
Most advice about car accidents is generic: exchange info, take photos, call your insurer. Florida adds one rule that changes everything, and almost nobody mentions it at the scene: you have just 14 days to get medical treatment or you forfeit your PIP benefits entirely. This is a plain-English playbook for the two weeks that matter most, in order, from the scene through day 14. For an interactive version that adapts to your situation, use our after-a-crash walkthrough.
At the scene (day of)
- Get to safety and check on everyone. Call 911 if anyone is hurt.
- Call the police and get a report. A report protects you, especially if the other driver later changes their story.
- Photograph everything: all vehicles, damage, positions, plates, and the other driver's insurance card.
- Exchange information but do not admit fault, and watch for staged-crash red flags like a stranger steering you to a specific clinic.
Within 14 days: the deadline that matters most
This is the step that catches Florida drivers off guard. To use your PIP coverage, you must seek initial medical treatment within 14 days of the accident. Miss that window and PIP will not pay, no matter how real the injury turns out to be. Whiplash and concussions often surface days later, so a prompt evaluation is the safe move even if you feel fine at the scene.
Notify your insurer promptly
Report the crash to your own insurer soon after it happens, even if you were not at fault. Policies generally require prompt notice, and in Florida's no-fault system your own PIP handles your injury bills first, regardless of who caused the crash. Be factual and brief: report what happened without speculating about fault or the extent of injuries you do not yet understand.
Document everything, then keep documenting
- Save the crash report number and a copy of the report once it is available.
- Keep every medical bill and record, and note the dates of each visit.
- Track your symptoms in a simple log, since injuries can evolve over the two weeks.
- Save all correspondence with insurers and providers, including names and dates.
What NOT to do
- Don't wait to see how it feels. The 14-day clock does not pause for you.
- Don't rush to settle or sign anything. An early offer is rarely a full one, and signing can waive rights.
- Don't skip the police report for a 'we'll handle it privately' arrangement, which invites disputes and fraud.
- Don't exaggerate a claim, which is insurance fraud and is prosecuted in Florida.
When it's serious
PIP is designed to cover your basic injury costs quickly, but it caps at $10,000 and does not pay for pain and suffering (see is $10,000 enough?). For a serious injury that crosses Florida's threshold, permanent injury, significant scarring, or loss of an important bodily function, you can step outside no-fault and pursue the at-fault driver directly. That is the point to talk to a Florida attorney.
Frequently asked questions
What is the 14-day rule after a Florida car accident?
What should I do first after a crash?
Why might my PIP only pay $2,500?
When should I contact a lawyer?
The first 14 days after a Florida crash follow a simple order: stay safe and document at the scene, get medical treatment within 14 days no matter how you feel, notify your insurer promptly, and keep meticulous records while you wait to see how injuries develop. The single rule that separates a smooth claim from a denied one is the 14-day deadline. Everything else is discipline, and this playbook, or the interactive walkthrough, keeps you on track.
Last updated: Sep 17, 2026
Sources & references
We cite Florida statutes, the FLHSMV, and industry bodies like the Insurance Information Institute. How we research and maintain these guides. Spotted an error? Tell us.
About the author
Eddie Ezekiel
Eddie Ezekiel is a product and data specialist who builds digital tools for the insurance industry, including the website of Golden Eagle, an established insurance and financial-services firm. He founded FloRider to translate Florida's confusing car-insurance rules into plain English, with every claim traced back to primary sources like the FLHSMV.
Related reads

The 5-Year True Cost of Owning a Car in Florida
A car costs far more than its sticker price. Over five years in Florida, insurance is nearly the single biggest cost of ownership, rivaling depreciation. We break down where the money actually goes, and the one big cost you can actually cut.

The Cheapest and Most Expensive Cars to Insure in Florida
The car you choose can quadruple your insurance bill. We show the cheapest and most expensive vehicles to insure, with cited 2025 numbers, why the gap is so wide, and how much extra Florida drivers pay on top.

The Real Cost of Driving Uninsured in Florida
Skipping car insurance in Florida to save money is a trap. Getting caught suspends your license and triggers an expensive FR-44; crashing uninsured adds personal liability and a lawsuit. We add up what it really costs, both ways.