
The 5-Year True Cost of Owning a Car in Florida
A car costs far more than its sticker price. Over five years in Florida, insurance is nearly the single biggest cost of ownership, rivaling depreciation. We break down where the money actually goes, and the one big cost you can actually cut.

Eddie Ezekiel
Published Sep 17, 2026 · 4 min read
Updated Sep 17, 2026

Image credit: Photo by Jakub Zerdzicki on Pexels
The sticker price is the smallest part of what a car costs you. Once you add depreciation, fuel, insurance, financing, and upkeep, owning a vehicle runs into the tens of thousands over just a few years. And in Florida, one line on that ledger is unusually large: insurance. Over five years at Florida's rates, car insurance nearly ties depreciation as the single biggest cost of ownership, far above what drivers in most states pay. Below, we break down where the money actually goes, why Florida insurance is so outsized, and the one big cost you can genuinely cut.
What it really costs to own a car
According to AAA's 2025 analysis, the average new vehicle driven 15,000 miles a year costs about $11,577 annually to own and operate, or roughly $965 a month. That figure blends every cost of ownership: depreciation, fuel, insurance, finance charges, maintenance, and registration. Over five years, it adds up to nearly $58,000 nationally, and more in an expensive-insurance state like Florida.
The 5-year breakdown, Florida-adjusted
Here is where Florida changes the picture. AAA's national breakdown puts insurance at about $1,694 a year. But Florida's average full-coverage premium is roughly $4,171, about 2.5 times higher. Swap Florida's real insurance cost into the model and the chart shifts dramatically: insurance leaps from a minor line to nearly the largest one, almost tying depreciation.
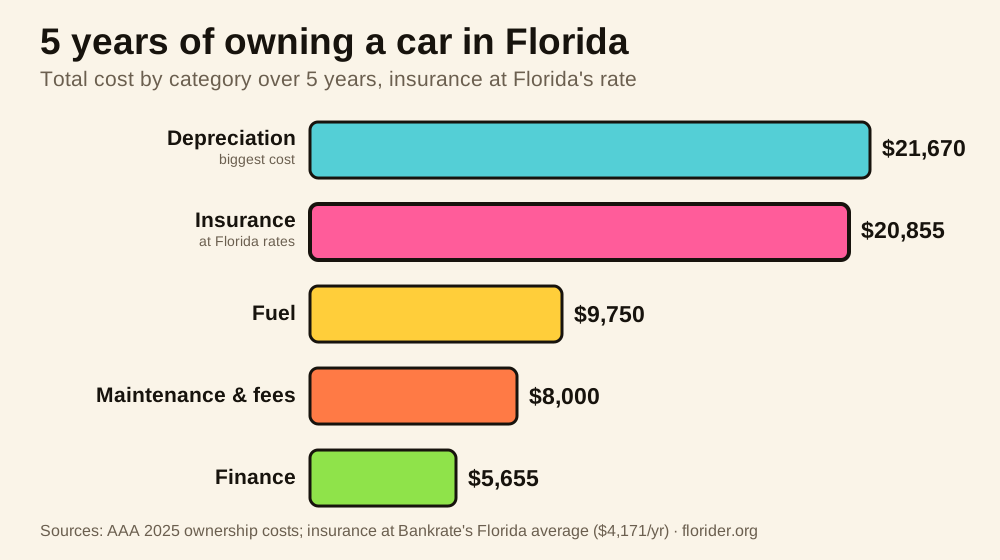
Image credit: FloRider, data from AAA (2025) and Bankrate
Insurance: the cost you can actually cut
Here is the useful part. Most of the big ownership costs are hard to change. Depreciation is baked into the car you bought. Fuel depends on prices and your commute. Finance charges are set by your loan. But insurance, nearly the biggest cost in Florida, is the one you can meaningfully lower right now, without changing your car or your commute:
- Compare several insurers at matching coverage; the spread can top $1,000 a year for the same driver.
- Raise your deductible if you can cover it, to lower the premium.
- Improve your credit over time, which Florida lets insurers price heavily.
- Claim every discount: multi-policy, multi-car, safe driver, low mileage, paid in full, autopay.
- Drop full coverage on an older car whose value no longer justifies comp and collision.
- Re-shop every year, since loyalty quietly raises the single most controllable big cost you have.
Trimming the other costs, briefly
- Depreciation: buy a lightly used car and hold it longer, so someone else eats the steepest first-year drop.
- Fuel: a fuel-efficient or hybrid model cuts the second-biggest operating cost over five years.
- Finance: a larger down payment and a shorter loan reduce total interest.
- Maintenance: keep up with routine service to avoid the expensive failures that come from skipping it.
Frequently asked questions
How much does it really cost to own a car?
What is the biggest cost of owning a car?
Why is insurance such a big share of ownership cost in Florida?
Which ownership cost can I most easily reduce?
Owning a car in Florida is a roughly $66,000 commitment over five years, and insurance is nearly the biggest piece of it, rivaling the depreciation you cannot avoid. That is the bad news. The good news is that insurance is also the most controllable of the big costs: you cannot un-depreciate your car or lower gas prices, but you can shop your policy, tune your coverage, and shave hundreds or thousands off the bill every year. In the most expensive state in the country, that is where the real savings live.
Last updated: Sep 17, 2026
Sources & references
We cite Florida statutes, the FLHSMV, and industry bodies like the Insurance Information Institute. How we research and maintain these guides. Spotted an error? Tell us.
About the author
Eddie Ezekiel
Eddie Ezekiel is a product and data specialist who builds digital tools for the insurance industry, including the website of Golden Eagle, an established insurance and financial-services firm. He founded FloRider to translate Florida's confusing car-insurance rules into plain English, with every claim traced back to primary sources like the FLHSMV.
Related reads

The Cheapest and Most Expensive Cars to Insure in Florida
The car you choose can quadruple your insurance bill. We show the cheapest and most expensive vehicles to insure, with cited 2025 numbers, why the gap is so wide, and how much extra Florida drivers pay on top.

The Real Cost of Driving Uninsured in Florida
Skipping car insurance in Florida to save money is a trap. Getting caught suspends your license and triggers an expensive FR-44; crashing uninsured adds personal liability and a lawsuit. We add up what it really costs, both ways.
What Your Credit Score Costs You on Florida Car Insurance
In Florida, credit can swing your car insurance more than almost anything else. A poor-credit driver pays about 138% more than one with excellent credit. We show the real numbers, why insurers do it, and how to lower your rate.