
What Happens If Your Car Is Towed After an Accident?
After a crash, a car that can't be driven gets towed, and the storage clock starts ticking that same day. We unpack who pays for the tow and storage, why moving fast matters, and how to get your car and belongings back.

Eddie Ezekiel
Published Aug 5, 2026 · 4 min read
Updated Sep 17, 2026
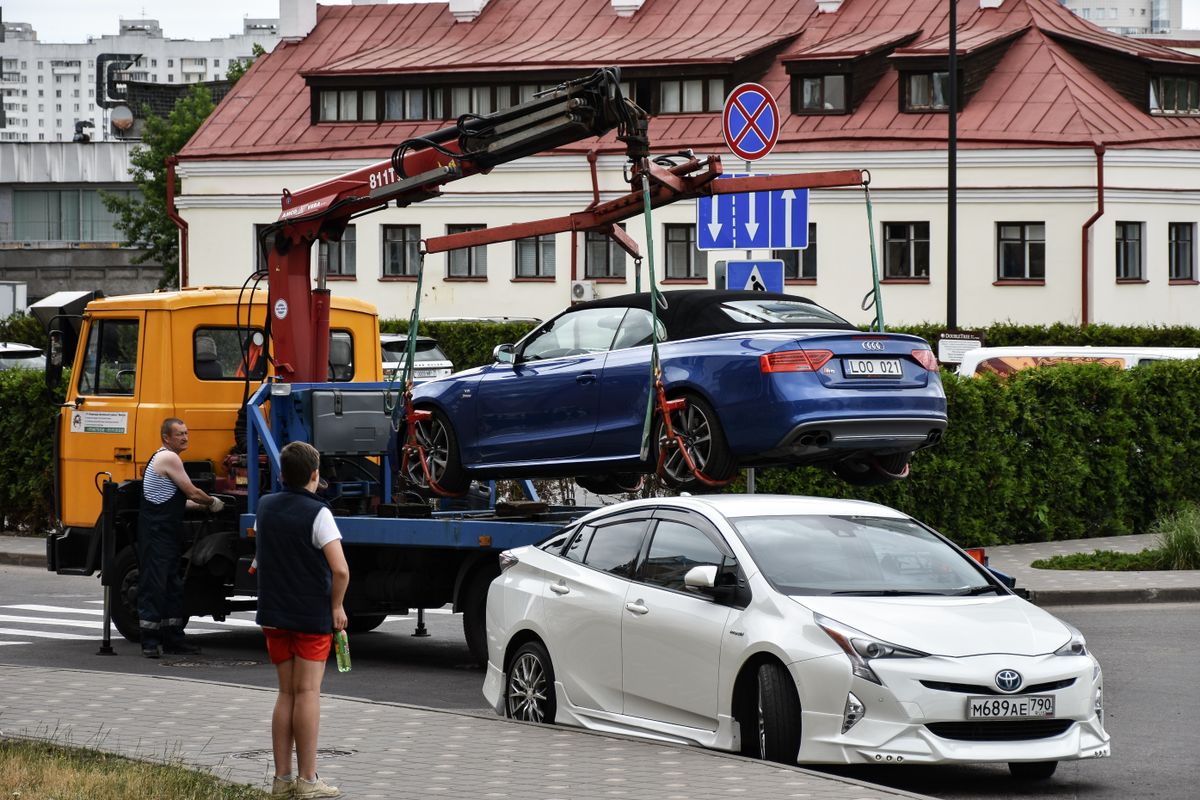
Image credit: Photo by Artem Makarov on Pexels
After a serious crash, if your car cannot be driven, it gets towed, usually to a storage or impound lot. And this is the part that surprises people: the meter starts running immediately. Storage fees accrue every single day the car sits, on top of the towing fee itself, and insurers cover reasonable storage, not unlimited storage. Below, we unpack who pays for the tow and storage, why the first 48 hours matter so much, and how to get your car and your belongings back.
Why the clock matters
A car towed from a crash scene usually lands at a storage lot, and that lot charges a daily storage rate on top of the towing fee itself. Those daily charges are the real danger, because they keep climbing whether or not anything is happening with your claim. Insurers cover reasonable storage, not an open-ended tab, so a slow response can leave you paying the difference out of pocket.
Who pays for the tow and storage
The good news is that towing and reasonable storage are usually covered, but by which coverage depends on the crash:
| Situation | What usually pays |
|---|---|
| The crash was your fault (or no-fault dispute) | Your own collision coverage tows the car and covers reasonable storage |
| The other driver was at fault | Their liability coverage can pay, though your collision may pay first and recover it |
| Non-crash damage (flood, fire, theft recovery) | Your comprehensive coverage |
| You carry only PIP and PDL | Neither covers towing your own car; the cost is on you |
If you only carry Florida's required minimum, note that PIP and PDL do not cover towing your own car. That is a job for collision or the at-fault party's coverage, which is one more reason the minimum leaves real gaps.
Move fast: the first 48 hours
- Get the tow details at the scene if you can: the towing company's name, phone number, and where the car is going.
- Call your insurer right away to open the claim and get direction on where the car should go.
- Ask about moving the car to an approved repair shop or storage, which is often cheaper than the impound lot.
- Keep every receipt for towing and storage so the claim reimburses what it should.
- Do not let it sit. The longer it stays, the more of the storage bill can fall to you.
Getting your car and belongings back
You generally have the right to retrieve personal belongings from a towed car, even while the vehicle itself is held. Bring your ID and proof of ownership, and be aware the lot may have limited hours and its own release process. To release the car itself, you typically need to settle the towing and storage charges (which your claim may reimburse) or have your insurer arrange the move, especially if the car is drivable after minor repairs.
If the car is a total loss
If the insurer declares the car a total loss, storage usually stops accruing once they take possession, since the car becomes theirs to dispose of. Do not keep paying storage on a car you no longer own. And remember you are typically owed its Actual Cash Value, which you can push back on if the first offer seems low. See how total loss is calculated.
Frequently asked questions
Who pays to tow my car after an accident in Florida?
Does insurance cover storage fees?
Can I get my belongings out of a towed car?
What happens to storage fees if my car is totaled?
A towed car after a Florida crash is a clock, not just an inconvenience. Storage fees run daily, collision or the at-fault driver's liability usually pays (the state minimum does not), and the difference between a covered bill and one you eat is mostly about speed. Get the tow details at the scene, call your insurer immediately, retrieve your belongings, and move the car promptly. Handle it fast and the tow is a footnote; let it sit and it becomes a second bill on top of the crash.
Last updated: Sep 17, 2026
Sources & references
We cite Florida statutes, the FLHSMV, and industry bodies like the Insurance Information Institute. How we research and maintain these guides. Spotted an error? Tell us.
About the author
Eddie Ezekiel
Eddie Ezekiel is a product and data specialist who builds digital tools for the insurance industry, including the website of Golden Eagle, an established insurance and financial-services firm. He founded FloRider to translate Florida's confusing car-insurance rules into plain English, with every claim traced back to primary sources like the FLHSMV.
Related reads

The 5-Year True Cost of Owning a Car in Florida
A car costs far more than its sticker price. Over five years in Florida, insurance is nearly the single biggest cost of ownership, rivaling depreciation. We break down where the money actually goes, and the one big cost you can actually cut.

The Cheapest and Most Expensive Cars to Insure in Florida
The car you choose can quadruple your insurance bill. We show the cheapest and most expensive vehicles to insure, with cited 2025 numbers, why the gap is so wide, and how much extra Florida drivers pay on top.

The Real Cost of Driving Uninsured in Florida
Skipping car insurance in Florida to save money is a trap. Getting caught suspends your license and triggers an expensive FR-44; crashing uninsured adds personal liability and a lawsuit. We add up what it really costs, both ways.